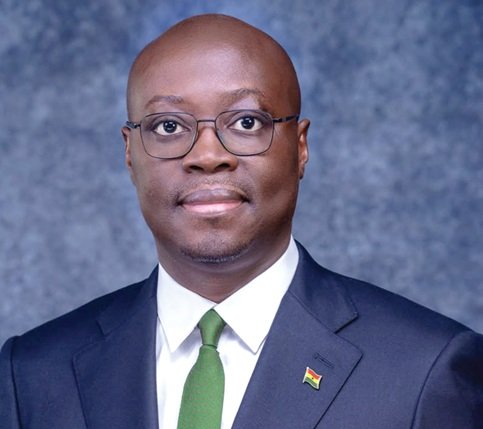
Finance Minister Dr Cassiel Ato Forson says the government has paid GH¢24.8 billion into statutory funds since January 2026, with the transfers intended to support education, healthcare, road maintenance, local development and other legally assigned purposes. The announcement followed the release of third-quarter statutory funds and was reported by Graphic Online, 3News, Citi Newsroom and Joy Business. It is a significant public-finance statement because the timing and reliability of statutory transfers affect institutions that plan services around money earmarked by law.
The announcement is also a starting point for accountability, not the end of it. The public summary does not provide a complete fund-by-fund schedule showing how much was due, how much was paid, when each transfer reached the receiving institution, or how the money was spent. Those details are needed to connect a headline total with actual services, projects and outcomes.
What statutory funds are intended to do
Statutory funds are allocations made under laws that assign revenue to particular purposes. The funds named in reporting on the GH¢24.8 billion announcement include the Ghana Education Trust Fund (GETFund), the Free Senior High School programme, the District Assemblies Common Fund, the National Health Insurance Fund, the Ghana Medical Trust Fund, the Road Maintenance Trust Fund, the Mineral Development Fund and the Mineral Income Investment Fund. Their mandates differ, but each is expected to support a defined public objective.
That earmarking can provide a degree of predictability. Education authorities may plan infrastructure or interventions, health institutions may budget for services, road agencies may schedule maintenance and district assemblies may prepare development programmes. When transfers are delayed or reduced, institutions can face pressure on cash flow, service providers may wait for payment and planned work can be postponed. Reliable transfers are therefore important even when the overall budget is under strain.
However, a transfer to a fund is not the same as a completed project or an improved service. The money may need to pass through additional administrative steps, procurement and implementation. A public-finance report should distinguish allocations, cash releases, amounts received by the fund, commitments, actual expenditure and results. Those stages help readers understand whether funds are available, whether they are being used and whether the intended public benefit is being delivered.
The context of capping and releases
Graphic Online’s report explained that statutory funds were affected by the Earmarked Funds Capping and Realignment Act, 2017 (Act 947), which placed ceilings on transfers and allowed amounts above the cap to be redirected to other budget priorities. The arrangement was intended to give government more flexibility in managing public finances, but it drew criticism from stakeholders who argued that it constrained the funds’ ability to meet obligations.
In 2025, the government announced measures to remove or reduce capping for selected funds, including GETFund, the National Health Insurance Fund and the Road Fund. The current payment announcement is presented by the Finance Minister as a departure from delays, capping and arrears. That is the government’s characterization of the change. A full assessment requires a comparison of the legal amounts due, actual transfers and outstanding obligations over a consistent period.
The phrase “on time and in full” is important because it makes a claim about both timing and completeness. To evaluate it, the public needs a clear schedule for each fund, the statutory basis for the amount due, the date the transfer was made and any adjustments or deductions. A single aggregate total can show the scale of the government’s stated payments, but it cannot by itself establish that every fund received every amount due on the date required.
What the GH¢24.8 billion figure tells us
The total indicates that the government says it has transferred substantial resources to statutory funds during 2026. It also signals that the administration wants to demonstrate improved fiscal management and support for public services. The statement matters to schools, health facilities, district assemblies, road maintenance agencies and other institutions that depend on these allocations.
But the public reports do not provide a detailed distribution of the GH¢24.8 billion among the named funds. Nor do they set out a comparable amount due under each law, a quarterly breakdown or a complete reconciliation against revenue performance. Without that information, readers should not invent percentages or assume that the funds received equal shares. Different funds have different legal bases and revenue streams.
It is also important to separate the announcement from the performance of the institutions receiving the money. A fund may receive an allocation and still face procurement delays, capacity constraints or project-management challenges. Conversely, a service may be improving for reasons that cannot be attributed to one transfer alone. Sound analysis looks at the whole chain from revenue collection and release to spending, delivery and independently assessed results.
Why citizens should ask for more detail
Public accountability does not require citizens to become accountants. It does require clear information. A useful release would show each fund’s opening balance, amount due during the period, amount transferred, date of payment, amount spent, commitments carried forward and any arrears. If the law permits adjustments, the reason and calculation should be explained. The information should be published in a format that can be compared from quarter to quarter.
For education, the public can ask how transfers relate to approved programmes and infrastructure. For healthcare, citizens can ask whether funds are reaching facilities and supporting the services for which they were earmarked. For roads, a transfer should be connected to maintenance schedules, contract payments and the condition of the network. For district assemblies, residents should be able to identify projects, budgets, contractors, milestones and completion status.
Those questions are not an accusation that money has been misused. They are the normal checks that make a public-finance claim meaningful. When an administration says it has paid a large total, the next step is to publish the evidence that lets people trace the money without relying solely on a press statement.
What the announcement means for fiscal management
Statutory transfers operate alongside other demands on the national budget, including wages, interest payments, capital investment and emergency spending. A government may face pressure to meet several obligations at once. Predictable transfers can help funds plan, but the fiscal system also needs transparency about revenue, cash management and competing priorities. A well-documented release schedule can show whether improved payment timing is supported by durable revenue performance or depends on short-term cash adjustments.
For businesses that supply public institutions, payment reliability matters too. Contractors, service providers and suppliers may have to pay workers and buy materials before receiving public payments. Clear information about fund releases can reduce uncertainty, although it cannot substitute for procurement discipline or contract management. The relationship between payment timing and service delivery is one reason public-finance data should be timely and accessible.
For citizens, the most useful question is not simply whether a total sounds large. It is whether the money is being transferred according to law, whether institutions can use it effectively and whether the resulting services meet public needs. The same standard should apply regardless of which political party is in office.
What to watch in the next budget and reports
Ghana’s 2027 Budget and subsequent financial reports will provide opportunities to compare claims with published figures. Readers should look for fund-specific allocations, actual releases, revenue assumptions, cash-flow information and audit findings. They should also look for explanations when a fund’s expenditure differs from its release or when a project is delayed. Clear reporting helps distinguish a funding problem from an implementation problem.
Oversight institutions, Parliament, auditors, civil society and the media all have roles in examining these details. The receiving funds should publish their own financial statements and programme reports where required. The Ministry of Finance can make the process easier by publishing a consolidated transfer table that uses consistent labels and dates. Such a table would allow the public to verify the aggregate without having to piece together separate announcements.
MyGHPages will continue to follow public-finance announcements and the data behind them. Readers can also review our earlier reporting on credit risks and affordable lending for Ghanaian SMEs and the GoldBod commitment to forest restoration, which illustrate why the details of public and institutional funding matter. Visit the MyGHPages homepage for more business coverage.