Ghana’s cybersecurity authorities are encouraging the public to remain alert and report suspicious activity as digital services become part of everyday life. Mobile money, online banking, social media and e-commerce make transactions faster, but they also create opportunities for fraudsters who rely on impersonation, stolen credentials and pressure tactics.
Common warning signs
Many scams begin with an unexpected call, text message or social media conversation. A person may claim to be a mobile money agent, bank employee, delivery worker or government official and ask for a PIN, one-time password or other confidential information. Some messages create urgency by claiming that an account will be blocked or a payment will be lost unless the recipient acts immediately.
Users should treat requests for PINs and verification codes as a major warning sign. Legitimate service providers should not need a customer to disclose a secret PIN to resolve a routine issue. Unexpected links, unfamiliar payment requests and offers that appear too good to be true also deserve careful checking.
Protect your mobile money account
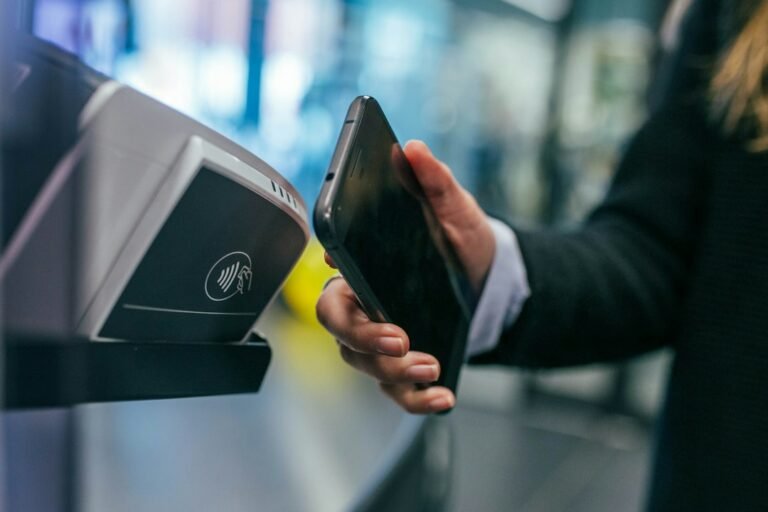
Use a PIN that is difficult for others to guess and do not share it with friends, relatives or people claiming to provide technical support. Avoid using birthdays or simple number sequences. Cover the keypad when entering your PIN in public and lock your phone when it is not in use.
Before approving a transaction, check the recipient name and amount displayed on the confirmation screen. If a stranger sends money and then asks you to return it to a different number, contact your provider through an official channel before taking action. Keep transaction alerts and report unfamiliar activity promptly.
Secure your phone and online accounts
Install operating-system and app updates from official sources. Use a screen lock, enable two-factor authentication where available and avoid installing applications sent through unknown links. Review app permissions and remove software you no longer use. On shared devices, sign out of financial accounts and avoid saving passwords in public browsers.
For email and social media, use unique passwords and recovery details that you control. A compromised email account can allow criminals to reset passwords on other services, so protecting it is especially important.
Businesses need basic controls too
Small businesses should separate personal and business payment records, restrict access to devices used for transactions and train staff to verify payment notifications independently. A screenshot or SMS shown by a customer is not the same as confirming that money has arrived in the business account. Reconcile transactions using the provider’s official application or statement.
Owners should also back up important records and agree on a clear process for changing payment numbers or supplier bank details. Any request to redirect a payment should be confirmed using a previously known contact, not only the phone number or email included in the new request.
What to do if you suspect fraud
Stop communicating with the suspected fraudster, contact your financial service provider through its official customer-care channel and report the incident to the relevant authorities. Preserve messages, phone numbers, transaction references and screenshots. Do not delete evidence while seeking help.
Digital safety is a shared responsibility. Simple habits—checking recipients, protecting verification codes, updating devices and reporting suspicious activity—can reduce the risk of financial loss. As more services move online, practical cybersecurity awareness is essential for households and businesses alike.
Source
Graphic Online – cybersecurity awareness reporting, November 5, 2026.