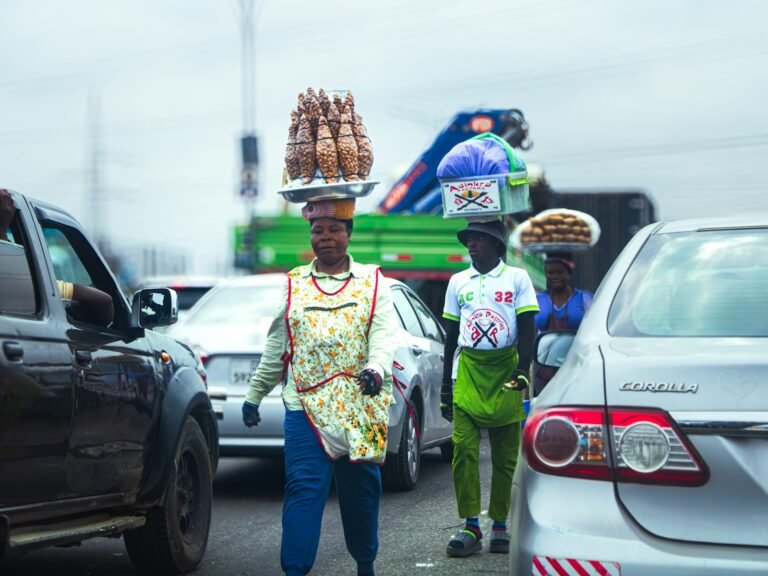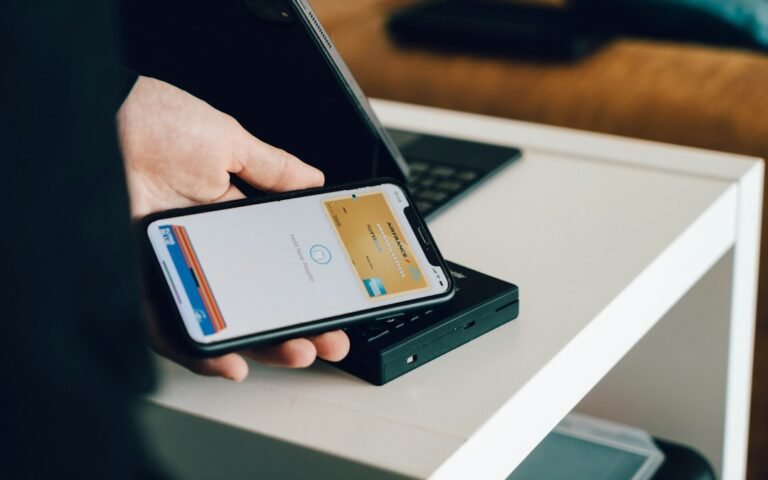
Digital payments are becoming an increasingly important part of doing business in Ghana. For small retailers, online sellers, food vendors, service providers and other micro and small enterprises, mobile money, bank transfers, cards and other electronic payment options can make it easier to receive money and keep transaction records.
But accepting digital payments is only one part of the challenge. Customers also need to feel confident that the business is legitimate, that the amount they are paying is clear, that their transaction will be recorded correctly and that problems will be handled professionally.
That makes customer trust one of the most important business advantages a Ghanaian small enterprise can build around digital payments.
Why digital payments matter to Ghanaian small businesses
Digital payments can reduce the friction involved in buying and selling. A customer may be able to pay without visiting a bank or carrying cash, while a business can receive confirmation of a transaction and maintain a digital record.
Research and policy work in Ghana also show that digital-payment adoption among enterprises still has room to grow. A 2025 report presented by the Institute of Statistical, Social and Economic Research (ISSER) and reported by the Ghana News Agency found that fewer than 37% of businesses in the study used or accepted digital payments. The report also identified concerns about fraud, limited understanding and uncertainty about the benefits as barriers to adoption. Ghana News Agency
For small businesses, this means that simply putting a mobile-money number on a poster is not enough. The payment process should be part of a wider customer-service system.
1. Use clear and consistent payment details
A business should clearly identify its official payment channels. If customers are paying through mobile money or a bank account, the business name and payment instructions should be easy to understand.
Avoid sending customers different payment numbers without explanation. If a business changes its account or mobile-money details, the change should be communicated through its official channels and verified internally before customers are asked to use it.
For businesses operating through WhatsApp, Facebook, Instagram or a website, the same official payment information should appear consistently wherever customers are instructed to pay.
2. Tell customers the full price before they pay
Unexpected charges can quickly damage trust. Businesses should explain the price of the product or service and identify additional costs such as delivery, installation, packaging or service fees before payment is made.
This is particularly important for online sellers. A customer who discovers an unexplained charge after transferring money may become reluctant to buy from the business again.
Clear pricing also reduces disputes because both the customer and the business have a shared understanding of what was purchased.
3. Give customers a transaction record
Businesses should keep accurate records of payments received. Depending on the type of business, this could include a digital receipt, invoice, order number, SMS confirmation, point-of-sale record or accounting entry.
Good records help when a customer says a payment has been made but the business cannot immediately identify the transaction. They also help the business track sales, identify outstanding payments and prepare better financial records.
For a growing enterprise, separating business transactions from personal spending can make financial management much easier.
4. Make fraud prevention part of customer service
Digital payments create convenience, but they also require businesses to take security seriously. Ghana’s payment-system strategy places strong emphasis on reliability, security, fraud prevention and consumer confidence. The Bank of Ghana’s National Payment Systems Strategy 2025–2029 identifies security and trust as important foundations for wider digital-payment participation. Bank of Ghana
Small businesses should therefore establish simple internal rules. Staff should know the official payment channels, understand how to verify unusual instructions and know who must approve a change in payment details.
Customers should also be warned about impersonation scams. A business should never ask customers to disclose passwords, PINs or one-time authentication codes as proof of payment.
5. Do not rely only on screenshots as proof of payment
A screenshot can be useful as supporting information, but businesses should use their own transaction records or official payment confirmation when verifying a payment.
This is especially important when an order has a high value. A seller should confirm that money has actually been received before releasing expensive goods or providing a service.
6. Build a professional online presence
Customers are more likely to trust a business when they can find consistent information about it. A small enterprise should, where practical, provide its business name, products or services, location or service area, opening hours, contact information and ordering instructions.
A simple website is useful, but a well-maintained business profile on a social platform can also provide important information. The key is consistency. Customers should be able to recognise which account belongs to the real business.
Ghana’s Information Services Department has also highlighted the importance of cybersecurity, consumer protection, skills and public trust as digital commerce develops. Information Services Department
7. Respond properly when a payment problem occurs
Even reliable payment systems can experience delays or failed transactions. The way a business responds can determine whether a temporary problem becomes a permanent loss of customer trust.
When a customer reports a payment problem, the business should check its records, explain what it knows, avoid making unsupported accusations and provide a clear next step.
If a refund is required, the business should explain the expected process and keep the customer informed rather than leaving the complaint unanswered.
8. Use genuine reviews and customer feedback
Trust is not built only through payment technology. Customer experience matters too.
Businesses should encourage genuine reviews and use complaints as information about where service can improve. Fake reviews may create short-term impressions, but they can damage credibility when customers discover that testimonials are not genuine.
For a new Ghanaian online business without many reviews, other signals can help: clear contact information, transparent pricing, identifiable business ownership, secure payment options and reliable communication.
9. Choose digital tools according to the business’s real needs
Not every small business needs an expensive software package. A trader may need a simple sales and inventory record, while a larger small enterprise may benefit from accounting software, customer management, stock control and integrated payment tools.
The goal should be to solve a business problem rather than accumulate technology. A payment system that is easy for customers and manageable for staff is often more useful than a complicated system nobody uses properly.
10. Keep business and personal finances organised
Using a personal account for business activity can make it harder to understand the real performance of an enterprise. Where appropriate, business owners should consider dedicated merchant or business payment arrangements and maintain separate records.
This can make it easier to calculate sales, expenses, profit and outstanding payments. It can also provide a clearer picture when the owner wants to apply for financing or expand the business.
What Ghanaian small businesses should prioritise
A practical trust-building checklist is simple:
- Display official payment details clearly.
- Confirm the total price before payment.
- Keep transaction and order records.
- Verify payments through official records.
- Train staff to recognise suspicious payment instructions.
- Never request customer PINs or one-time authentication codes.
- Publish reliable contact and business information.
- Respond quickly and professionally to payment disputes.
- Use genuine customer reviews.
- Choose digital tools that match the size and needs of the business.
The wider opportunity for Ghana’s digital economy
Ghana has already developed important foundations for a more cash-lite economy, including payment infrastructure, connectivity and a supportive policy environment. The Ministry of Finance’s country diagnostic on digital payments has also identified challenges such as consumer preference for cash, business preferences for cheques and interoperability issues. Ghana Ministry of Finance
For small businesses, the opportunity is therefore larger than simply accepting mobile money. Digital payments can support better records, easier customer communication, online commerce and access to broader markets when they are combined with sound business practices.
Frequently asked questions
How can a small business make customers trust its digital payments?
Use consistent official payment details, provide clear prices, confirm transactions properly, keep records and communicate professionally when problems occur.
Should businesses accept payment screenshots?
A screenshot can support a customer’s claim, but the business should verify the transaction using its own official payment record before releasing valuable goods or services.
Should a business use a personal mobile-money account?
Businesses should consider appropriate merchant or business payment arrangements where available. Keeping business and personal transactions organised can make accounting and reconciliation easier.
What information should a small online business publish?
Useful information includes the business name, products or services, prices or pricing method, location or service area, contact channels, delivery terms and official payment instructions.
What is the biggest mistake businesses make with digital payments?
One common mistake is treating payment technology as separate from customer service. A trusted payment process also requires clear pricing, accurate records, security procedures and responsive support.
Conclusion
Digital payments can help Ghanaian small businesses make transactions easier and build better records, but technology alone does not create trust. Customers need to know who they are paying, how much they are paying, what happens after payment and where to turn if something goes wrong.
Small businesses that combine secure payment practices with transparent pricing, reliable records, genuine customer service and a professional online presence can build stronger relationships with customers and create a better foundation for sustainable growth.