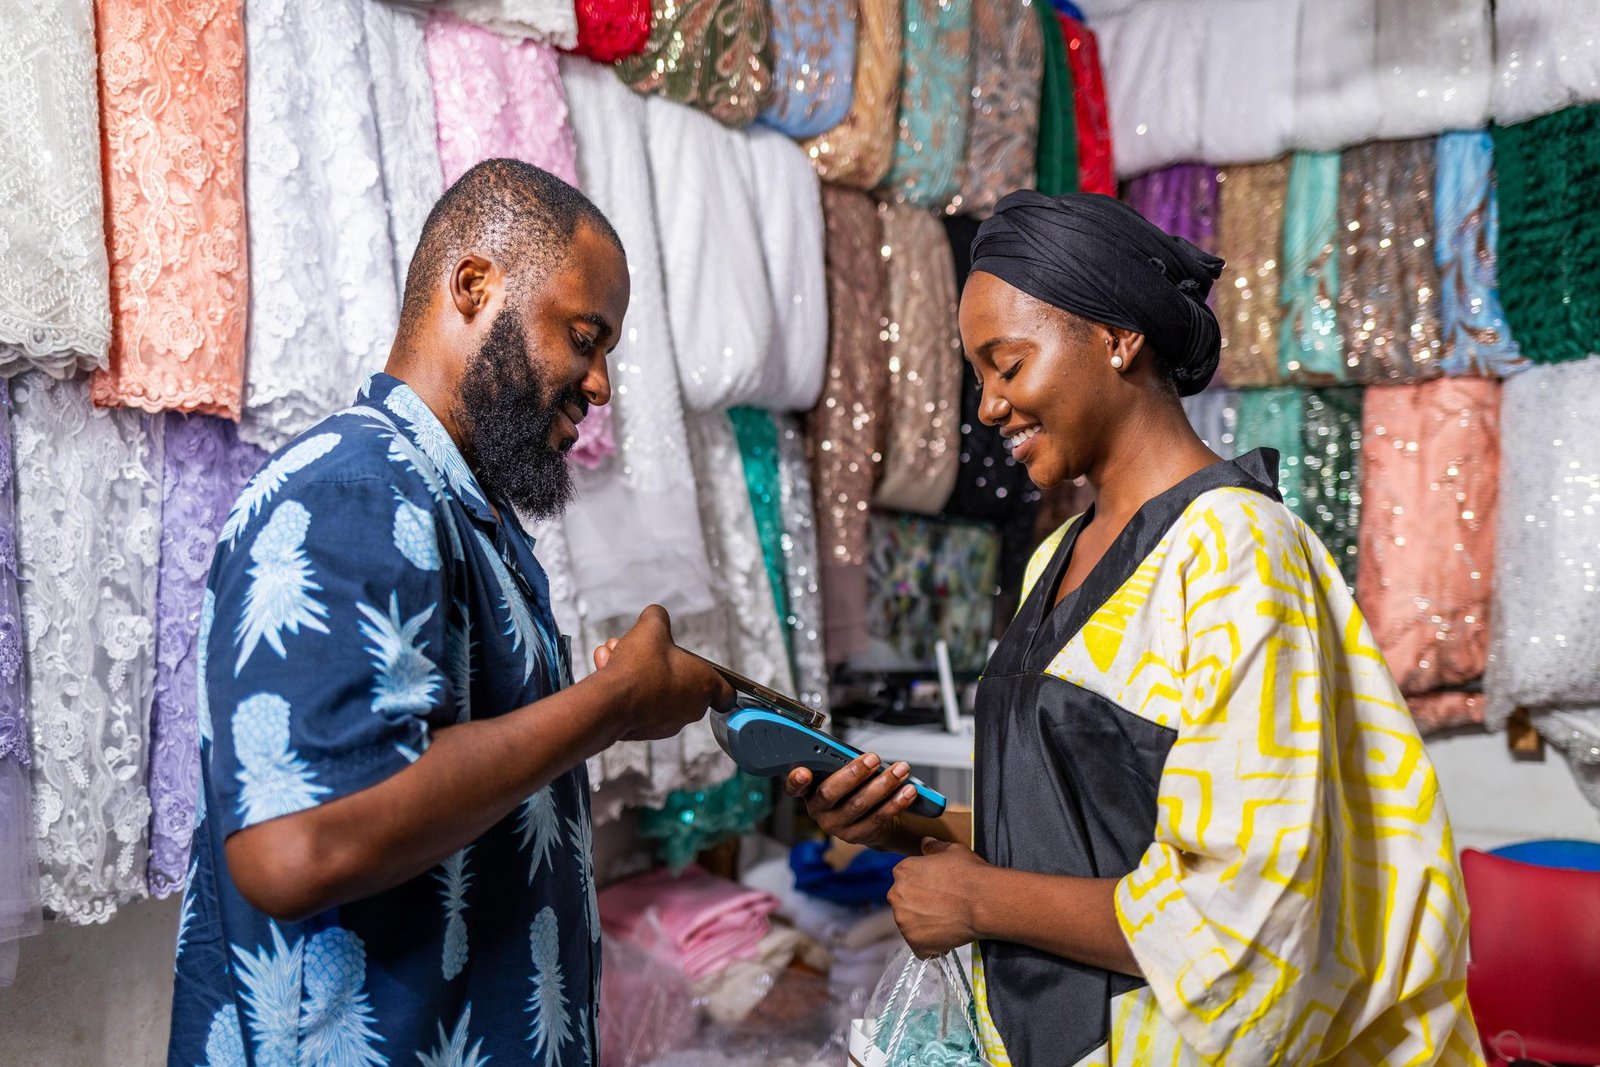
Digital payment systems help Ghanaian businesses manage customer transactions, sales records and financial operations.
Digital Payments for Ghanaian Small Businesses: Fees, Records and Fraud Prevention
By MyGHPages Business Desk
Digital payments are becoming an essential part of running a successful small business in Ghana. From market traders and retail shops to online sellers, restaurants, transport operators and service providers, businesses are increasingly accepting mobile money, bank transfers, payment cards and other electronic payment methods.
The shift towards cashless transactions is creating new opportunities for businesses to serve customers, improve payment convenience and maintain better financial records. However, accepting digital payments also introduces important responsibilities, including managing transaction fees, reconciling sales, protecting customer information and preventing fraud.
For small businesses operating with limited capital, even relatively small transaction charges can affect profitability when they accumulate over hundreds of payments.
The challenge is therefore not simply to accept digital payments. Business owners must understand what they are paying, how money moves into their accounts and how to maintain reliable records of every transaction.
According to the Bank of Ghana’s Payment Systems Oversight Annual Report 2025, mobile money transaction values increased by 50.8 per cent to approximately GH¢4.54 trillion in 2025, compared with GH¢3.01 trillion in 2024.
The report also recorded approximately 9.70 billion mobile money transactions during the year, demonstrating the importance of electronic payments in Ghana’s economy.
For Ghanaian entrepreneurs, understanding this changing payment environment can help improve business operations and reduce avoidable financial losses.
1. Why Digital Payments Matter to Small Businesses in Ghana
Traditional cash payments remain important, particularly for informal traders and businesses operating in local markets. However, relying entirely on cash can create challenges.
Business owners must manage physical cash, arrange deposits, monitor cash shortages and maintain accurate records of daily sales.
Digital payments offer an alternative by allowing customers to pay electronically using mobile money wallets, bank accounts, cards and supported payment applications.
Some important benefits include:
Convenience for customers: Customers can pay without carrying large amounts of physical cash.
Faster payment confirmation: Businesses can confirm transactions through official applications and account dashboards.
Improved financial records: Electronic transactions create references that can support bookkeeping and reconciliation.
Online business opportunities: Sellers can receive payments from customers who order through websites, social media and messaging platforms.
Reduced cash-handling risks: Businesses that receive more electronic payments may reduce the amount of physical cash stored on their premises.
Better financial visibility: Transaction histories can help owners understand sales patterns, monitor cash flow and identify unusual activities.
These advantages can be particularly useful for small businesses that want to grow beyond their immediate communities.
However, digital payments should complement good financial management rather than replace it.
2. Digital Payment Options Available to Ghanaian Businesses
There is no single payment method suitable for every business. The right choice depends on customer preferences, transaction volume, operating costs and the type of goods or services being sold.
Mobile Money Merchant Payments
Mobile money is widely used across Ghana and offers a convenient way for customers to pay businesses electronically.
A registered merchant arrangement can allow a business to receive payments through supported mobile money services.
Before registering, business owners should establish:
- The merchant registration requirements.
- The applicable transaction charges.
- Whether the service supports business transaction records.
- The settlement arrangements.
- How failed payments and disputed transactions are handled.
- Whether customer payments can be exported for accounting purposes.
Businesses should use official merchant accounts rather than treating personal wallets as a complete business accounting system.
Bank Transfers
Bank transfers can be useful for businesses receiving payments from customers, suppliers and corporate clients.
They are particularly relevant for larger transactions where customers prefer to pay directly into a business bank account.
Businesses should confirm the payment through their actual bank account rather than relying on screenshots or messages supplied by customers.
They should also check transfer processing times, charges and the availability of transaction statements.
Card Payments and POS Terminals
Point-of-sale terminals allow businesses to accept supported debit and credit card payments.
They can be useful for supermarkets, restaurants, hotels, pharmacies, retail shops and other businesses with regular customer traffic.
The Bank of Ghana reported that the number of deployed POS terminals increased from 15,597 in 2024 to 18,117 in 2025, representing growth of 16.2 per cent.
This expansion reflects the continued development of Ghana’s electronic payment infrastructure.
Before obtaining a POS terminal, businesses should compare equipment costs, merchant discount rates, settlement arrangements, maintenance charges and technical support.
Online Payment Gateways
Businesses selling products through websites or applications may need an online payment gateway.
Payment gateways can support different payment methods, depending on the provider and merchant agreement.
They may be useful for:
- Online retail shops.
- Hotel and accommodation bookings.
- Event ticket sales.
- Subscription services.
- Educational services.
- Digital product sales.
- Delivery and ordering platforms.
Before integrating a payment gateway, confirm its supported payment methods, transaction fees, settlement schedule, refund procedures and security requirements.
Interoperable Digital Payments
Ghana’s payment infrastructure also supports interoperability between participating financial institutions and payment service providers.
The Bank of Ghana identifies interoperability and real-time payment services as important developments in the country’s payment ecosystem.
For businesses, this can improve the ability to receive and transfer funds across supported payment channels.
The important consideration is to confirm which payment methods a provider actually supports and whether additional charges apply.
3. Understanding Digital Payment Fees and Business Costs
One of the most important decisions a small business must make is choosing an affordable payment arrangement.
Transaction charges vary depending on the provider, payment method, merchant agreement and transaction type.
A business should never assume that the fee advertised for one service applies to every digital payment.
Some charges to investigate include:
Merchant transaction fees: The amount deducted by a payment provider when a customer completes a payment.
Settlement fees: Charges associated with transferring collected funds into a designated bank account or wallet, where applicable.
Withdrawal charges: Costs associated with withdrawing money from an account or wallet.
POS equipment costs: Purchase, rental, maintenance or replacement costs associated with payment terminals.
Gateway charges: Fees associated with processing payments through an online payment platform.
Refund and chargeback costs: Potential expenses arising from disputed transactions, refunds or reversals.
Monthly service charges: Some arrangements may include recurring service or subscription costs.
How to Compare Payment Providers
Before signing an agreement, ask each provider for a written fee schedule.
Use the following comparison:
| Cost area | What to investigate |
|---|---|
| Transaction fee | Percentage or fixed amount |
| Settlement | Time and applicable charges |
| Withdrawals | Cost of accessing funds |
| Equipment | Purchase or rental price |
| Refunds | Reversal and dispute costs |
| Monthly fees | Recurring charges |
| Support | Availability and response time |
A simple way to estimate transaction expenses is:
Estimated transaction cost = Transaction amount × Merchant fee percentage
For illustration only, if a provider charges an assumed merchant fee of 1.5 per cent on a GH¢100 transaction, the processing fee would be GH¢1.50.
This is a mathematical example, not an advertised or recommended Ghanaian provider rate.
Businesses should also calculate their monthly costs.
For example, a shop processing 300 transactions per month should estimate its total fees using the actual transaction amounts and the provider’s written pricing terms.
The cheapest advertised rate may not necessarily be the best arrangement if settlement is slow, customer support is unreliable or additional charges apply.
4. How Small Businesses Can Maintain Accurate Digital Payment Records
Accepting electronic payments does not automatically guarantee accurate accounting.
Business owners must ensure that every transaction is recorded correctly and matched against the goods or services sold.
Poor record-keeping can create confusion when customers request refunds, suppliers demand payment or tax information is required.
A simple daily reconciliation system can make a significant difference.
Information Every Business Should Record
For each transaction, maintain:
- Transaction date.
- Transaction time.
- Customer or order reference.
- Amount charged.
- Payment method.
- Transaction reference number.
- Provider fee, where applicable.
- Net amount received.
- Refund or reversal status.
- Final settlement date.
These records can be maintained using a spreadsheet, accounting application or suitable business management system.
Example of a Daily Payment Record
| Date | Payment method | Sales amount |
|---|---|---|
| Monday | Mobile money | GH¢850 |
| Monday | Bank transfer | GH¢500 |
| Monday | Card payment | GH¢300 |
| Total | GH¢1,650 |
This is an illustrative example rather than actual business transaction data.
At the end of the day, the business owner should compare the sales ledger with the transaction histories provided by each payment provider.
Any difference should be investigated before the records are finalised.
Why Daily Reconciliation Matters
Suppose a shop records GH¢1,650 in electronic sales but receives only GH¢1,500 in its settlement account.
The owner should not immediately assume that GH¢150 represents transaction fees.
Possible explanations include pending settlements, refunds, failed transactions, deductions, separate transactions or recording mistakes.
The correct procedure is to examine the individual payment references and provider statements.
This makes it easier to identify discrepancies and prevent inaccurate financial reporting.
5. Ghana Revenue Authority and Digital Business Records
Tax compliance is another important reason for maintaining reliable payment records.
The Ghana Revenue Authority provides electronic services to help taxpayers manage tax obligations and business documentation.
One important development is the Electronic VAT System, commonly known as E-VAT.
According to the GRA, E-VAT is an electronic invoicing system for VAT-registered businesses. It is designed to improve the issuance and verification of VAT receipts and strengthen record-keeping.
The GRA explains that its E-VAT system can be installed free of charge for VAT-registered businesses that do not already have an appropriate system. Businesses with existing invoicing software may also be able to integrate it.
Under Ghana’s VAT reforms effective January 1, 2026, the standard effective VAT rate on taxable supplies is 20 per cent, comprising:
- 15 per cent Value Added Tax.
- 2.5 per cent National Health Insurance Levy.
- 2.5 per cent Ghana Education Trust Fund Levy.
Business owners should confirm their VAT registration status, applicable tax obligations and treatment of their particular transactions directly with the GRA.
Accepting mobile money or bank transfers does not automatically determine a business’s tax obligations. Tax treatment depends on the applicable rules and the nature of the business activity.
Maintaining invoices, receipts, transaction records and expense documentation can make tax administration easier.
Businesses can visit the official GRA E-VAT information page for guidance.
6. Fraud Risks Facing Ghanaian Small Businesses
Digital payments provide convenience, but they also expose businesses to different forms of fraud.
Fraudsters may target business owners, employees, customers and suppliers using social engineering, impersonation and fake payment notifications.
The Cyber Security Authority has specifically warned about fraudulent online business impersonation schemes.
In an advisory issued on April 30, 2026, the CSA reported 54 cases involving fake online business listings between January 1 and April 26, 2026, resulting in financial losses of GH¢266,195.
The fraudsters created fake business profiles on search engines and map services, then used fraudulent contact details to deceive customers.
Some victims were persuaded to disclose mobile money PINs or make payments to fraudulent accounts.
This is a serious warning for businesses that depend on online visibility and digital transactions.
Common Digital Payment Scams
Fake payment screenshots: Criminals send manipulated screenshots claiming that they have paid for goods.
Mobile money reversal scams: Fraudsters claim to have transferred money incorrectly and demand a refund.
Business impersonation: Criminals create fake social media accounts or online listings using the name of a legitimate business.
Fake supplier requests: A criminal impersonates a supplier and asks the business to transfer money to a different account.
Phishing messages: Fraudsters send links pretending to come from financial institutions or payment providers.
Unauthorised account access: Criminals attempt to obtain passwords, PINs or one-time verification codes.
Business owners should train employees to recognise these tactics and report suspicious requests immediately.
7. Practical Fraud Prevention Measures for Small Businesses
Protecting digital payments requires clear procedures that employees can follow consistently.
Verify Every Payment Before Releasing Goods
Never release products based solely on an SMS screenshot or a message displayed on another person’s phone.
Confirm the payment inside the official merchant application, bank account or payment dashboard.
Protect Merchant PINs and Passwords
Keep passwords, PINs and one-time passwords confidential.
Do not share account recovery codes with callers claiming to be technical support staff.
Use Official Payment Channels
Obtain payment services from legitimate providers and verify their regulatory status where required.
The Bank of Ghana provides information about approved payment service providers and relevant regulatory requirements.
Separate Employee Responsibilities
Where practical, avoid allowing one employee to control every aspect of the payment process.
For example, one employee may receive customer payments while an authorised manager reviews settlements and reconciles daily records.
Establish a Refund Policy
Create a clear procedure for handling customer complaints, failed transactions, duplicate payments and legitimate refunds.
Always verify the original transaction before issuing a refund.
Secure Business Devices
Use screen locks, strong passwords, software updates and appropriate security controls.
Do not leave payment devices unattended or allow unauthorised individuals to access merchant accounts.
Back Up Financial Records
Keep secure backups of invoices, receipts, transaction reports and accounting records.
A business should be able to retrieve its financial information even if a phone, computer or payment device is damaged or lost.
8. What to Do When a Business Experiences Digital Payment Fraud
Speed matters when a business suspects an unauthorised transaction or account compromise.
The owner should immediately contact the affected bank, mobile money operator or payment service provider using its official customer-support channel.
Request assistance with securing the account and investigating the transaction.
Preserve important evidence, including:
- Transaction reference numbers.
- Payment notifications.
- Suspicious telephone numbers.
- Email and WhatsApp conversations.
- Screenshots of fraudulent requests.
- Account statements.
- Relevant dates and transaction amounts.
Ghana’s Cyber Security Authority also operates a 24-hour cybersecurity and cybercrime reporting service.
Businesses and individuals can report incidents through:
Call or SMS: 292
WhatsApp: 0501603111
Email: report@csa.gov.gh
Website: https://www.csa.gov.gh/
Where financial services are involved, businesses should also follow their provider’s official complaint procedures and escalate unresolved regulatory complaints through the appropriate channels.
Reporting an incident does not guarantee recovery of lost money, but prompt action can assist investigations and may help limit further losses.
9. How to Choose the Right Digital Payment Provider
The best payment provider is not necessarily the one with the most advertisements or the lowest promotional price.
A small business should consider its operational needs before signing up.
Ask the following questions:
- Is the provider appropriately authorised to offer the service?
- What are the current merchant transaction charges?
- Are there additional withdrawal or settlement costs?
- How quickly will collected funds become available?
- Can transaction records be downloaded?
- Does the service support the payment methods customers prefer?
- How are failed transactions and refunds handled?
- Is customer support available when problems occur?
- What security measures protect merchant accounts?
- Are there additional costs for equipment or monthly services?
The Bank of Ghana’s official financial technology and innovation resources provide information on the licensing and oversight of payment service providers.
Businesses should verify providers rather than relying entirely on recommendations from social media groups or informal agents.
10. A Practical Digital Payment Strategy for Ghanaian Entrepreneurs
Small businesses do not need to introduce every available payment method immediately.
A gradual approach can reduce costs and make financial management easier.
First: Identify customer preferences.
Find out whether customers mainly use mobile money, bank transfers or card payments.
Second: Compare providers.
Request written fee schedules and compare the complete cost of each service.
Third: Start with essential payment methods.
Introduce the options most relevant to customers and test the process using small transactions.
Fourth: Create a daily accounting routine.
Record every sale and compare provider statements with business records.
Fifth: Train employees.
Ensure that workers understand payment verification, fraud prevention and refund procedures.
Sixth: Review business performance monthly.
Calculate total digital sales, transaction expenses, refunds, failed payments and settlement delays.
This process helps business owners determine whether digital payment services are improving efficiency and profitability.
Frequently Asked Questions About Digital Payments for Ghanaian Small Businesses
Which digital payment method is best for a small business in Ghana?
There is no single best option for every business. Mobile money, bank transfers, POS terminals and online payment gateways serve different needs. Compare customer preferences, charges, settlement times and provider reliability before choosing.
Do mobile money merchants pay transaction fees?
Merchant charges depend on the service, provider and applicable merchant agreement. Request the current written fee schedule before registering. Do not assume personal wallet charges and merchant charges are identical.
How should a small business record mobile money payments?
Record the transaction date, amount, reference number, customer order, payment method and applicable charges. Reconcile these records against the official provider statement daily.
Does the Ghana Revenue Authority accept electronic business records?
The GRA provides electronic tax and invoicing services, including E-VAT for VAT-registered businesses. Business owners should confirm which invoicing and record-keeping requirements apply to their particular circumstances.
How can businesses avoid fake mobile money payment screenshots?
Verify every transaction using the official merchant application, account dashboard or provider statement before releasing goods or services.
What should a business do after a fraudulent payment?
Contact the financial service provider immediately, secure the affected account, preserve transaction evidence and report the incident to the Cyber Security Authority through 292.
Conclusion: Digital Payments Must Improve Business Profitability
Digital payments are becoming increasingly important to Ghana’s commercial environment.
The growth of mobile money, bank transfers, POS terminals and online payment services provides opportunities for businesses to serve customers more conveniently and improve their financial operations.
However, adopting digital payments without understanding the costs and risks can create unnecessary financial pressure.
Small business owners must compare transaction charges, maintain accurate sales records, reconcile payments regularly and establish strong fraud-prevention procedures.
They should also understand their tax responsibilities and use appropriate invoicing and record-keeping systems.
The objective should not simply be to become a cashless business. It should be to build a more efficient, secure and financially organised business.
For Ghanaian entrepreneurs, good digital payment management can support better customer service, improved financial visibility and sustainable business growth.
MyGHPages will continue providing practical business, finance and technology information to help Ghanaian entrepreneurs make informed decisions.
Visit https://myghpages.com/ for more Ghanaian business news, financial developments and practical guides.
Authoritative External Sources and Further Reading
- Bank of Ghana – Payment Systems Oversight Annual Report 2025
- Ghana Revenue Authority – Electronic VAT System (E-VAT)
- Bank of Ghana – FinTech and Innovation
- Cyber Security Authority – Fraudulent Online Business Impersonation Schemes
- Ghana Interbank Payment and Settlement Systems – GhanaPay Frequently Asked Questions
Editorial note: Transaction fees vary by provider and agreement. No universal merchant fee is stated in this article. Businesses should verify current pricing directly with their selected providers.
1 thought on “Digital Payments in Ghana: Fees, Records and Fraud Prevention”